Understanding Medicare: A Simple Guide to Medicare Coverage
Is your 65th birthday getting closer? You have probably started seeing a lot more Medicare mail. For many people, understanding Medicare can feel confusing at first.
There are different parts, enrollment periods, and coverage choices. When you are just starting out, that can feel like a lot to take in.
This guide keeps it simple. We will break Medicare into easy steps and walk through what it is, who qualifies, how enrollment works, and what your main coverage options look like.
What Is Medicare?
Medicare is a federal health insurance program mainly for people who are 65 and older. It helps pay for many common healthcare services, like hospital care, doctor visits, and preventive care.
For many Americans, Medicare becomes the base of their healthcare coverage in retirement.
The program has been around for decades and now covers millions of people across the country. It helps make healthcare easier to access and manage as we get older.
Medicare vs Medicaid
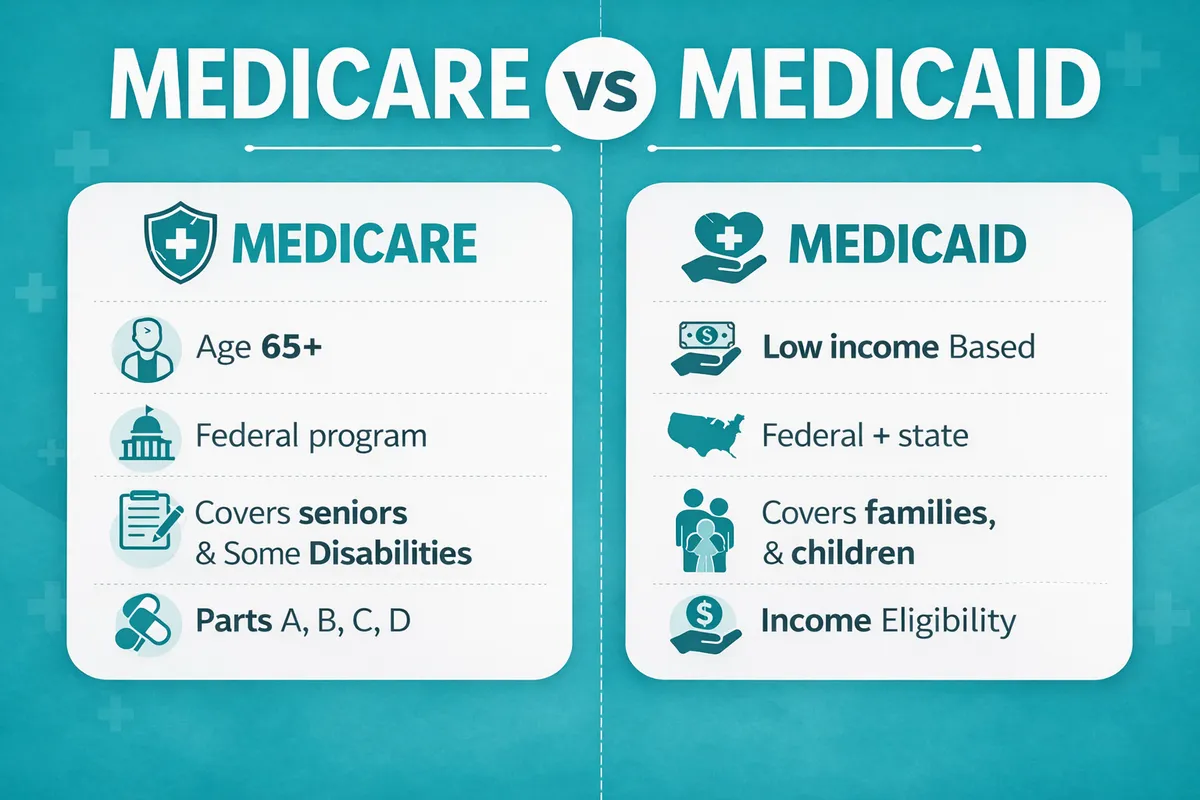
Medicare and Medicaid are easy to mix up because the names sound so alike, but they do different jobs.
Medicare is a federal health insurance program mostly for people 65 and older, plus some younger people with disabilities. Eligibility is usually based on age or disability, not income.
Medicaid is run jointly by the federal government and each state. It provides healthcare coverage for people with limited income and resources.
Some people qualify for both programs at once. This is called dual eligibility, and it can help cover more healthcare costs.
When Do You Become Eligible?
Most people become eligible for Medicare when they turn 65.
Age is not the only path, though. People who have received Social Security Disability Insurance for 24 months can also become eligible.
Certain conditions, like ALS or End-Stage Renal Disease, may allow someone to qualify sooner.
Knowing when you qualify is an important first step in planning your Medicare coverage.
How Do You Enroll in Medicare?
There are two main ways Medicare coverage begins: automatic enrollment and self enrollment.
Automatic Enrollment
If you are already getting Social Security benefits at least 4 months before you turn 65, you will usually be enrolled in Medicare Part A and Part B automatically.
Your Medicare card usually arrives in the mail about 3 months before your 65th birthday.
Self Enrollment⏰
If you are not getting Social Security benefits yet, you will need to sign up for Medicare yourself.
Most people sign up during their Initial Enrollment Period. This is a seven month window that includes:
• The 3 months before the month you turn 65
• The month you turn 65
• The 3 months after
Signing up during this window can help you avoid a gap in coverage and a possible late enrollment penalty. If you or your spouse still have job-based coverage, your timing may be different.
The Different Parts of Medicare
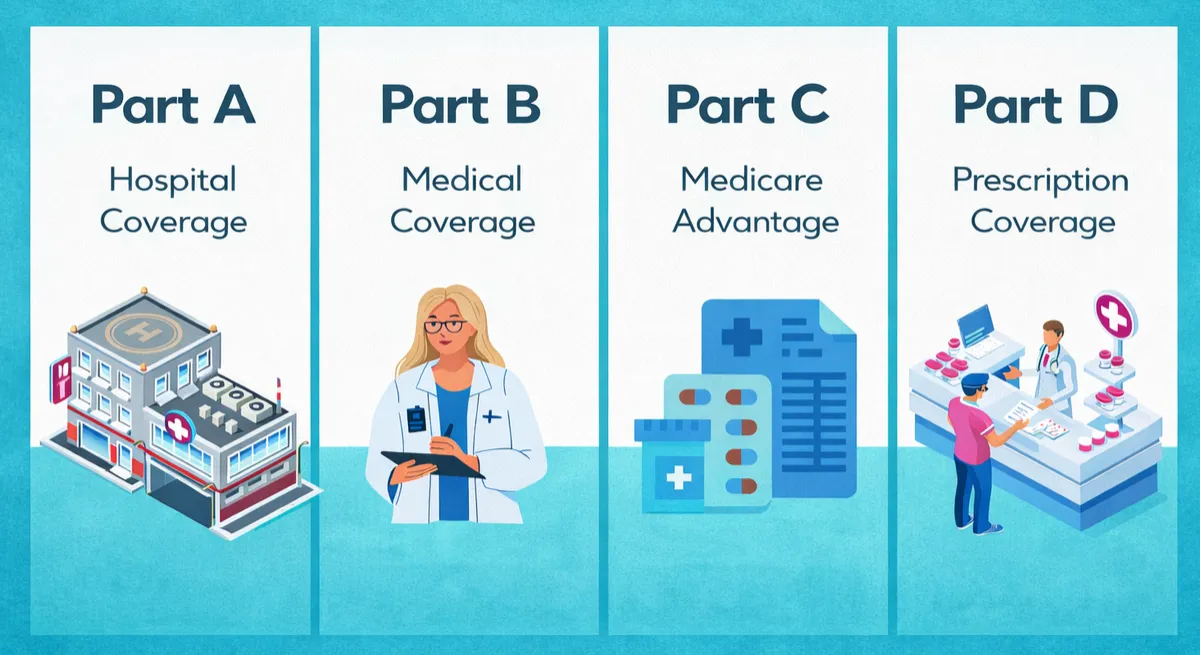
Medicare is divided into sections called parts. Each part helps cover a different type of care.
Knowing what each part does makes the program much easier to navigate.
Medicare Part A🏥
Medicare Part A is your hospital coverage.
This can include inpatient hospital stays, skilled nursing care after a qualifying hospital stay, hospice care, and some home health care.
Most people do not pay a monthly premium for Part A if they or their spouse paid Medicare taxes for at least 10 years while working.
Medicare Part B🧑⚕️
Medicare Part B covers outpatient medical services.
This includes doctor visits, preventive screenings, lab work, and certain medical equipment.
Part B helps pay for much of the routine care people use during the year.
Medicare Part C📋
Medicare Advantage, also called Part C, is another way to get your Medicare benefits.
These plans are offered by private insurance companies approved by Medicare. They must cover the medically necessary services Original Medicare covers, and some plans add extra benefits.
Medicare Part D 💊
Medicare Part D helps pay for prescription drugs.
You can buy it as a separate drug plan alongside Original Medicare, or get it as part of a Medicare Advantage plan.
Each plan has its own list of covered drugs, called a formulary.
How Much Does Medicare Cost?
One of the most common questions people ask is what Medicare will cost.
Medicare helps with healthcare expenses, but it is not completely free. Like most insurance, there are still costs involved.
Depending on your coverage, those costs may include:
• Monthly premiums
• Deductibles
• Copayments
• Coinsurance
Here are the standard 2026 amounts for Original Medicare:
• Part A premium: $0 for most people, up to $565 a month for others
• Part A deductible: $1,736 per benefit period
• Part B premium: $202.90 a month (higher incomes pay more)
• Part B deductible: $283 a year, then usually 20% of the Medicare-approved amount
These are the 2026 amounts. They change every year, and new numbers are usually announced in the fall, so check Medicare.gov for the latest.
Because of these out of pocket costs, many people explore extra coverage to help manage their expenses.
Coverage Gaps in Original Medicare
Original Medicare includes Part A and Part B, but it does not cover every healthcare cost.
You may still pay deductibles, copays, and coinsurance, and Original Medicare alone has no yearly limit on out of pocket costs. Because of these gaps, many people consider additional coverage.
Medigap vs Medicare Advantage
Two common options people compare are Medigap and Medicare Advantage.
Medigap, also called Medicare Supplement Insurance, works with Original Medicare and helps pay some of the out of pocket costs Parts A and B leave behind.
Medigap has its own monthly premium, and most people add a separate Part D plan. In return, you can generally see any doctor in the U.S. who accepts Medicare, and your costs tend to be more predictable.
Medicare Advantage is another way to get your Medicare benefits through a private insurance company approved by Medicare.
Medicare Advantage plans often have lower monthly premiums, and many include drug coverage. You still pay your Part B premium. Most plans use a provider network, some services need approval first, and what you pay depends on the care you use.
Every Medicare Advantage plan has a yearly limit on what you pay out of pocket for covered Part A and Part B services.
You cannot use a Medigap policy with a Medicare Advantage plan, so most people choose one path or the other.
Timing matters too. Your Medigap Open Enrollment Period is the 6 months that start the month you are 65 or older and have Part B. Outside that window, depending on your state, a Medigap company may be able to ask health questions.
Vision and Dental Coverage
Original Medicare generally does not cover routine vision and dental care.
Medicare usually covers eye care only when it relates to a medical condition, like glaucoma or cataracts.
It also generally does not cover routine dental care like cleanings, fillings, or dentures.
Some Medicare Advantage plans offer extra vision and dental benefits, and coverage varies by plan. People with Original Medicare can also buy separate dental or vision insurance.
Getting Help With Medicare
If Medicare feels like a lot, you are in good company. Many people feel confused when they first start learning about it.
Because of this, some people choose to work with licensed insurance agents or brokers who can explain coverage options and compare plans.
Educational workshops can also help. Free, unbiased help is available from Medicare.gov and 1-800-MEDICARE.
Spending a little time understanding Medicare now can make the process smoother and help you feel more confident about your coverage decisions.
Key Takeaways: What to Remember About Medicare
For millions of Americans, Medicare is a big part of managing healthcare costs in retirement.
It may seem complicated at first, but learning the basics, like eligibility, enrollment periods, and the parts of Medicare, makes it much easier to navigate.
Starting early and learning your options can help you choose coverage that fits your healthcare needs and your budget.
IMPORTANT NOTE: This guide is for general educational purposes only. It is not personalized insurance, legal, or financial advice. It is not affiliated with or endorsed by the U.S. government, the Centers for Medicare & Medicaid Services (CMS), or the federal Medicare program. Medicare rules, coverage, and costs can change, often every year. For official information, visit Medicare.gov or call 1-800-MEDICARE (1-800-633-4227), TTY 1-877-486-2048. For help with your own situation, talk with a licensed insurance agent at Avelan Health: (505) 408-5984.
